
Definition of Assured Launch
For the purposes of UK policy, assured launch should be defined as the ability to place a required payload into orbit, in a timely and affordable manner, when national or commercial needs require it, including response to unprogrammed or unwarranted events. “Assured” means having sufficient confidence that access to orbit will remain available in crisis or conflict, as well as routine peacetime conditions.
Assured launch is not synonymous with sovereign launch. Sovereign launch is one means of delivering assurance, but it is not the only one. Assured launch may be delivered through allied, commercial, or partnered arrangements where those arrangements provide sufficient confidence of access. Sovereign launch, by contrast, should be understood as a UK-owned, procured and UK-operated launch capability from UK territory or an overseas territory, where the UK controls the relevant launch system, infrastructure, permissions, access and operational prioritisation with control of the associated supply chain.
The core policy issue is therefore not launch for its own sake, but assured access to an operational and economic effect. In peacetime, this includes routine launch for recapitalisation, planned capability insertion and technology demonstration. In crisis or war, it includes the responsive and rapid reconstitution or augmentation of space capability where satellites have been degraded, lost, denied or no longer provide the communications, ISR, PNT or other effects required by UK armed forces.
Current UK Approach
The UK’s current approach to assured launch relies on allied, specifically US, capability, much of which is delivered through commercial launch providers, rather than a fielded sovereign military launch capability. This capability, both in terms of ground launch infrastructure and launch vehicle provider is currently based internationally. MoD has agreements and relationships in place with allied nations to support access to space in crisis or conflict. These arrangements provide the basis for current assurance, although they have not been tested under the pressures of a major crisis or warfighting scenario, where allied priorities, commercial capacity and political considerations (or non-state-owned control of capability) may differ from peacetime conditions and national priorities.
 SaxaVord spaceport in Scotland
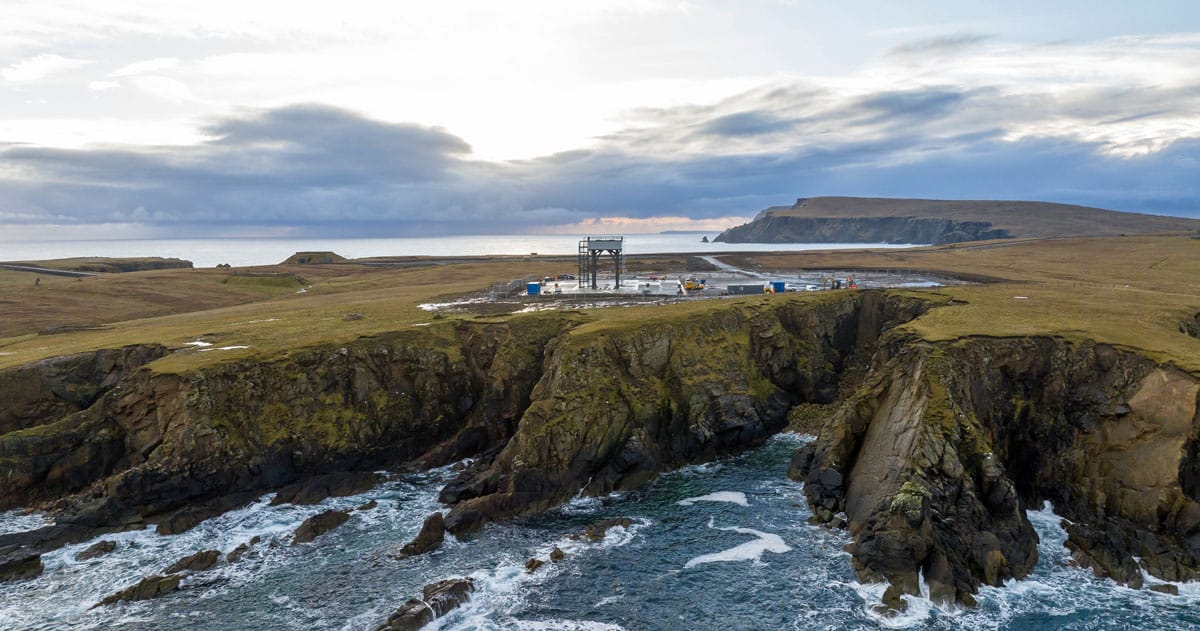 SaxaVord spaceport in Scotland
In parallel, the UK Space Agency leads efforts to develop launch from the UK through engagement, monitoring of market developments and alignment with HMG requirements where appropriate. MoD does not currently fund UK launch capability directly, nor has it defined a specific Defence requirement for UK sovereign launch around which industry can plan. The current position is therefore to observe how UK launch capability develops and assess how it may contribute to future Defence assurance. The Defence Investment Plan (DIP) infers an uplift in launch requirement if it is to meet the 2030-2035 targets for capability in areas such as Space Domain Awareness and Rendezvous and Proximity Operations and this has yet to be translated into a future requirement.
The UK Space Agency is investing in the UK launch ecosystem, including spaceport infrastructure and enabling activity to support commercial launch from the UK. Following Orbex entering administration, the resultant near-term capability is likely to be UK-based ground infrastructure used by overseas-owned launch companies, such as RFA and HyImpulse. This could still provide a UK-based launch option to polar orbits, which are particularly important for ISR missions. Other UK launch providers remain at an earlier start-up stage and are not expected to field operational capability in the short term. If a UK requirement for assured launch is needed, independent of other state or non-state providers, then early signalling of intent will be an important step.
The Assurance Gap
The difficulty is that the requirement for assured launch is becoming more acute at the same time as the assumptions underpinning allied or commercial access are becoming less certain.
Space is now a congested, contested and competitive operational domain. Adversaries understand the UK’s reliance on space services and are increasingly able to exploit satellite vulnerabilities through electronic warfare, cyber capabilities, directed-energy weapons, co-orbital ASAT systems and direct-ascent ASAT missiles. Russian activity has included direct-ascent anti-satellite testing, on-orbit activity involving deployable sub-satellites, contestation of the electromagnetic spectrum and actions that created significant debris in low Earth orbit. China is also assessed as having a robust direct-ascent ASAT programme, co-orbital-relevant capabilities and widely used electronic and cyber counter-space capabilities.
The implication is that assured launch can no longer be treated as a peacetime procurement issue alone. Alongside the economic opportunity of benefiting from a growing global commercial launch requirement, it must increasingly be treated as a warfighting reconstitution requirement. If adversaries can dazzle, jam, spoof, cyber-attack, manoeuvre against or physically destroy satellites, then the UK must be able to restore or augment space-derived effects at the pace required by operations or for economic stability.
This creates a challenge for reliance on singular allied launch capacity. In peacetime, allied and commercial access is sensible and cost-effective. In crisis or high-intensity conflict, however, allied orbital assets and launch capacity are likely to be under pressure from the same threat environment. Analysis of forecast launch demand and supply to 2040 suggests that, whilst aggregate Western launch capacity appears sufficient, European launch capacity alone is unlikely to meet growing European demand from the early 2030s onwards, leaving both the UK and Europe reliant on US providers for a significant proportion of launch access [1].
When tested against a stress scenario in which US launch capacity is unavailable due to wartime prioritisation, geo-political constraints or unilateral decisions by commercial providers, UK and European launch supply becomes insufficient, resulting in a deficit of approximately 223 tonnes by 2033 and 703 tonnes by 2040, equivalent to a shortfall of around 50% of combined UK and European demand by 2040. In such circumstances, launch capacity would become a scarce and highly contested resource.
This shortfall would affect commercial operators as well as government and Defence customers. The removal of US capacity would force European institutional, defence and commercial demand to compete for a much smaller pool of available launches. In a severely supply-constrained market, governments may still be able to secure services by paying a substantial premium, underwriting dedicated missions or using national-security prioritisation mechanisms. Many commercial operators would not have the same financial or political leverage. They could instead face higher launch prices, longer delays, displacement from manifests and, in some cases, an inability to close their business case or deploy their payloads at all. The result in a wider economic resilience gap affecting UK space companies and the downstream services that depend on them.
 SpaceX launch of Intelsat IS-40e mission
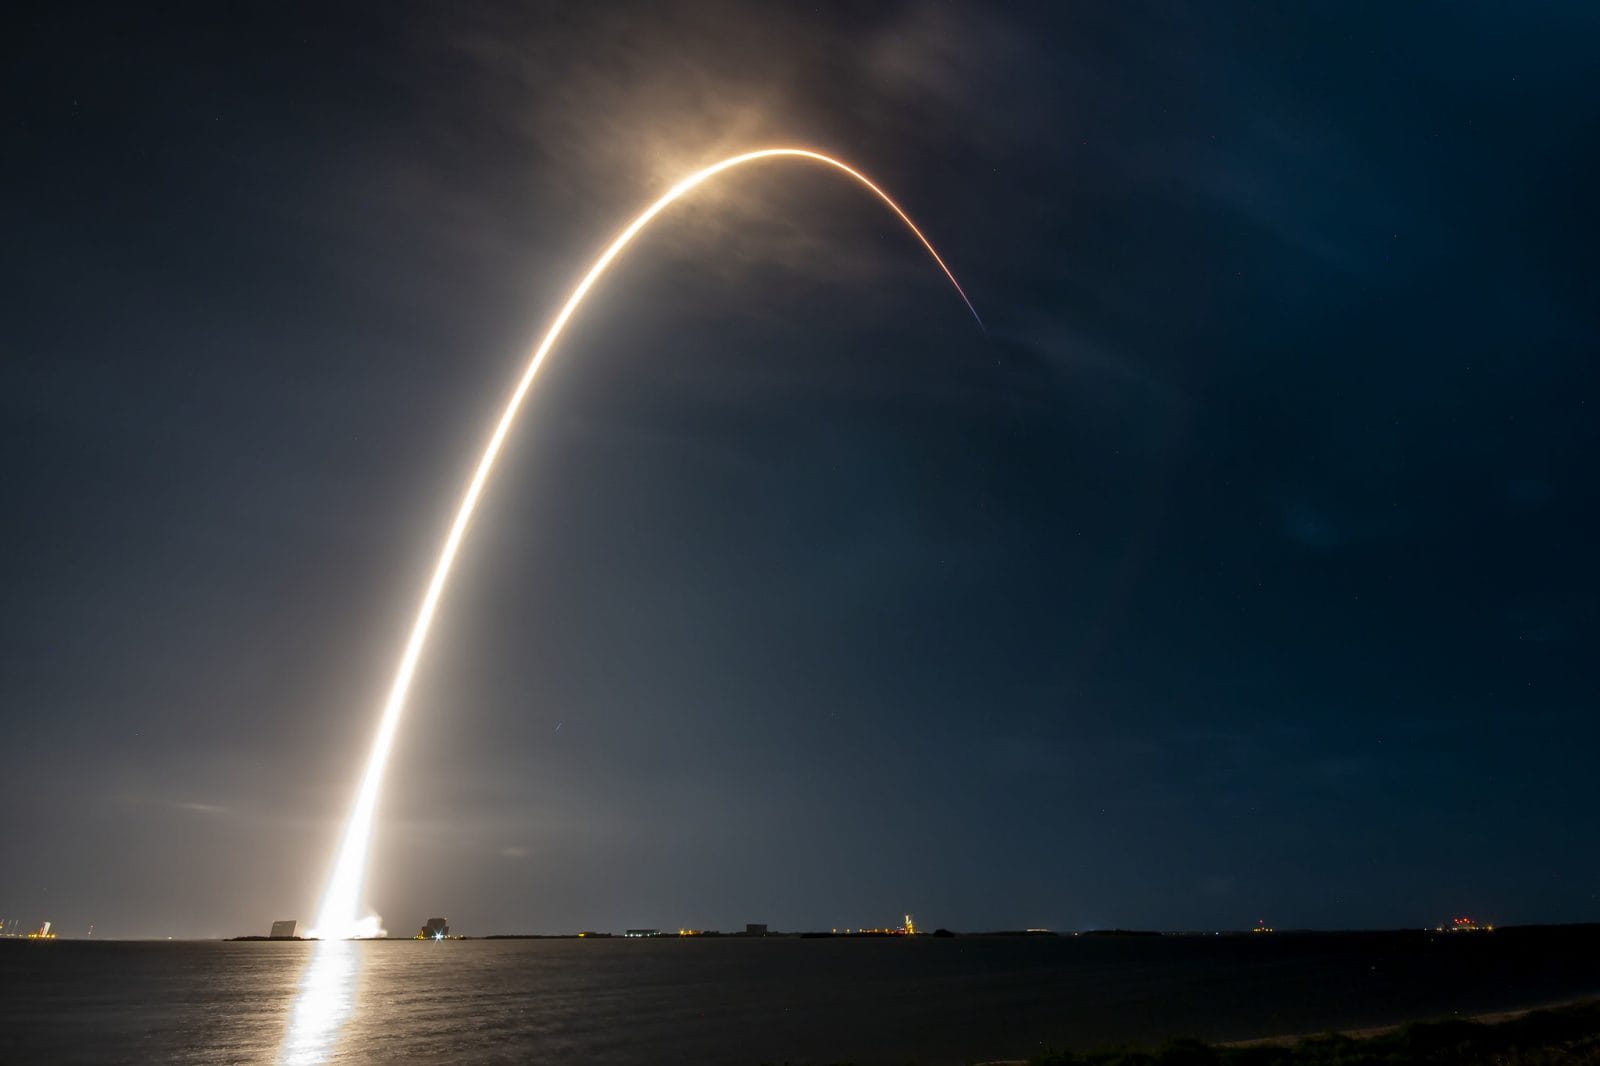 SpaceX launch of Intelsat IS-40e mission
Where European allies are themselves engaged, launch capacity may be prioritised against their own sovereign military requirements and economic interests, while allies not directly participating in UK operations may judge that providing launch services carries escalation, legal or political risk. The UK may also find it increasingly difficult to secure prioritisation for its payloads within a demand-dominated European launch market, particularly given its position outside the European Union and the potential for European governments and institutions to favour domestic or EU requirements. The issue is therefore not only whether allied launch capacity exists, but whether it will be available, prioritised and politically releasable at the point of UK need. The same test must be applied to UK commercial payloads. Even where European launch capacity remains technically accessible, scarce slots are likely to flow towards customers with the greatest purchasing power or strongest sovereign backing. UK commercial operators could consequently be priced out or deprioritised, particularly where they are competing with European national programmes, institutional missions or defence requirements.
The pursuit of assured launch access is not solely a UK consideration. Germany has emphasised access to space as a prerequisite for defence and deterrence and is considering a Bundeswehr-owned launch site to protect military missions from competition for commercial capacity [2]. This provides a practical example of an ally examining greater national control as a means of strengthening launch assurance.
There is also a second, more fundamental constraint: launch is only useful if the UK has something ready to launch. The United Kingdom currently lacks both a credible responsive launch capability and a sufficiently developed inventory of launch-ready payloads that could be deployed at short notice to reconstitute or augment capability. MoD’s planned investment in ISR, SATCOM, SDA, Space Control, PNT and C2 has not yet been defined beyond 2030 although the DIP would indicate it is substantial. The responsive launch proposition will remain incomplete unless it is matched by modular satellites, prepared payloads, ground systems, mission data pipelines, licensing, integration processes and rehearsed operational concepts. This also has an economic aspect for critical energy, financial and PNT services to the UK and society.
The result is that UK assured launch policy must address two linked questions: how the UK gets to orbit, and what capability it is able to put there at operational speed. Without both, assured launch risks becoming an aspiration rather than a credible military reconstitution mechanism.
Implications for UK Launch Strategy
The appropriate approach is to continue relying upon allies and commercial providers in the short to medium term, while deliberately and materially backing the development of a sovereign UK launch capability as a strategic option over the longer term. This need not imply that every UK payload should be launched nationally, nor that MoD should bear sole responsibility for funding a dedicated launch programme. Rather, it implies a One-Government approach in which MoD defines the operational requirement, the UK Space Agency and Department for Business, Innovation, Science and Trade help shape the civil requirement and commercial launch ecosystem, and industry is given a clear demand signal against which to invest and mature capability.
The UK should take three practical steps.
First, HMG should scenario plan assured launch with allies, building on its experience of Schreiver War Games, NATO scenarios and contingency planning within the Defence Scenario Book and National risks managed by the Cabinet Office. This should test whether allied and commercial launch access would remain available in the most demanding crisis scenarios, including where allied orbital assets are also under threat, where launch capacity is saturated, or where political willingness to support a UK operation is uncertain. The purpose should not be to displace allied reliance, but to understand where reliance is robust, where it is fragile, and where the UK needs greater sovereign choice. This would also help identify where a differentiated UK launch offer could strengthen NATO and allied resilience, rather than duplicate existing allied capability.
Scenario planning should include the impact of launch-capacity disruption on UK commercial operators and the wider economy. It should examine what would happen if US capacity became unavailable and government customers absorbed or drove up the price of remaining European supply. While Defence may secure scarce services through sovereign prioritisation or a greater willingness to pay, commercial operators could be delayed, displaced or priced out entirely. HMG should identify strategically important commercial space services, consider mechanisms to preserve commercially viable access to orbit during severe scarcity (such as diversification of launch provision through other international partners or existing national spaceports), and assess whether denial of access to launch should be included as a distinct risk in the National Risk Register.
Second, HMG should set clear, operationally relevant requirements for UK assured (and sovereign if necessary) launch that can be developed with industry over a 5–10-year horizon. Work needs to start now, but the results will take time. These requirements should be framed around the operational and economic effect required, not simply the existence of a launch vehicle or spaceport. Requirements should be based on anticipated future solution architectures, not heritage systems and must include industry involvement in their development. They should include the payload classes, orbital profiles, responsiveness timelines, security standards, integration processes, mission assurance requirements and command-and-control arrangements that would make UK launch useful to Defence. Constraints must also be identified. UKSA can then use those requirements to encourage industry to develop a launch service that is credible, investable and aligned with national security need. A strong, sustained institutional demand signal would also help leverage private capital. Its absence has previously undermined capital-raising efforts; establishing credible Government demand could make the difference in securing the investment needed to deliver capability.
Third, the UK Government should develop a clear responsive payload strategy in partnership with UK industry, based on national strategic risks and capability need, again as a 5–10 year proposition that must begin now. Launch only becomes operationally relevant if there are payloads ready, or near-ready, to launch. HMG should identify which space-derived effects would most need rapid reconstitution or augmentation in crisis; for example ISR, communications resilience, SDA, PNT support or tactical data relay, and then work with industry to build a pipeline of modular satellites, hosted payloads, ground systems, licensing pathways and mission operations processes to support them. Industry involvement must ensure that the strategy reflects technological maturity, practical delivery constraints and the capabilities of available and emerging solutions. Without this, assured launch risks becoming an industrial aspiration rather than a credible warfighting reconstitution mechanism.
The strategic case for UK launch is therefore not merely industrial or economic; it is increasingly strategic and operational. As adversary counter-space capabilities continue to evolve, and as both the UK and its allies are likely to require space reconstitution capacity in wartime, the demand signal for assured launch will only increase. A UK assured launch option should therefore be developed not as an alternative to allies, but as a contribution to allied resilience: a differentiated service offering focused on responsive small-satellite launch, high-assurance payload handling, rapid integration, polar and high-inclination access, and close coupling between launch, payload and operational effect. This would underwrite UK assurance for military, economic and societal space capabilities, strengthen the UK’s offering to allies, and provide an alternative route to orbit for commercially and strategically important payloads that might otherwise be priced out, delayed or displaced when international launch capacity is most constrained.
Authors:
Ian Annett – Chair, UKspace Launch Committee
James Cornish – Vice Chair, UKspace Launch Committee
Bibliography
[1] Frazer-Nash Consultancy, ‘UK Launch Demand and Supply to 2040: An Evidence Based Assessment’
[2] A. Parsonson, ‘Germany Considers Dedicated Launch Facility for its Armed Forces’, European Spaceflight, 28.7.26